

This piece was first published on my Forbes column here.
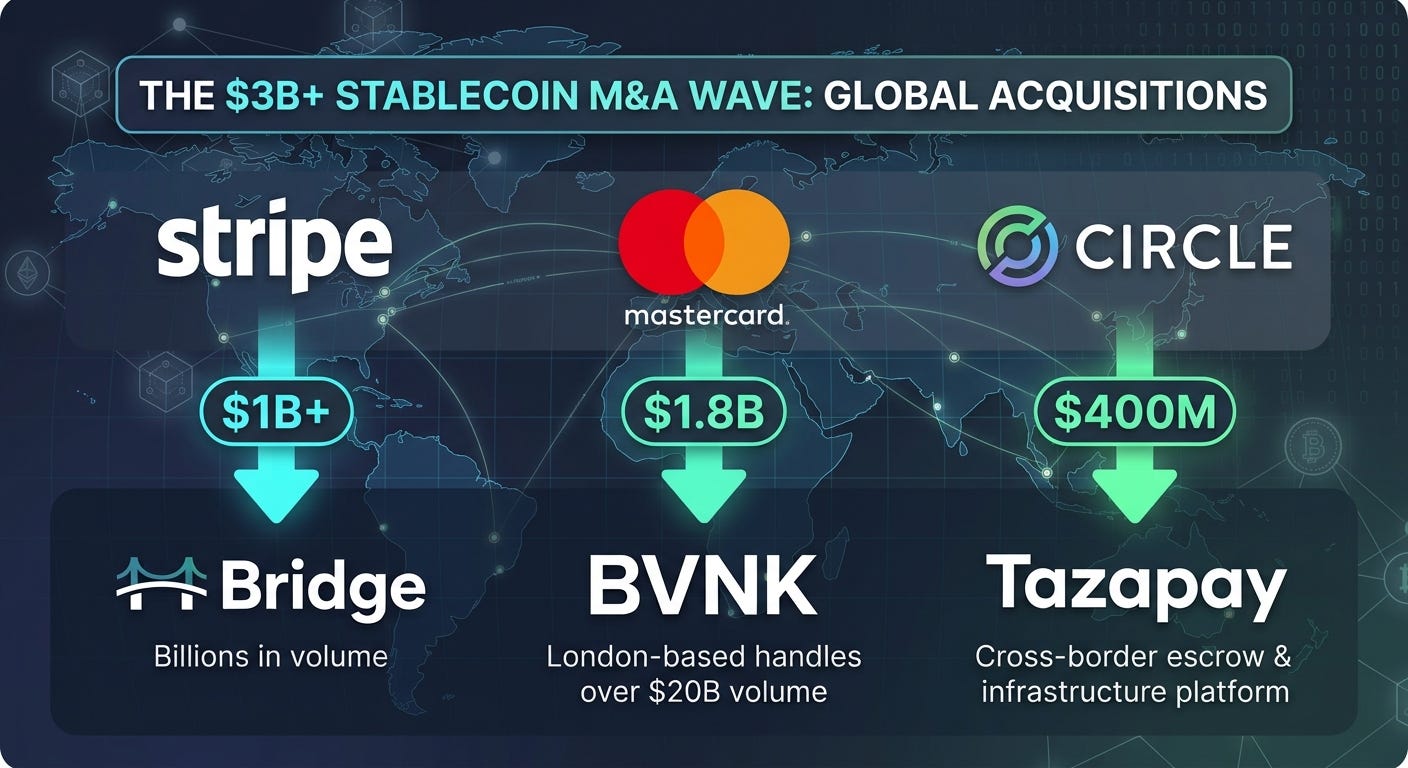
Over the last 2 years, three different buyers paid over $3b for three different stablecoin operators around the world.
First, Stripe bought Bridge in the United States, followed by Mastercard buying London’s BVNK and more recently Circle, which is buying Singapore’s Tazapay. Together, the three companies had raised roughly $200 million and were founded in 2022, 2021 and 2020 respectively.
It doesn’t feel like a fluke: that’s three different types of strategic buyers, purchasing similar companies in different geographies. While the rationale for each deal was different, they each offer a valuable lesson.
The State Of Play
A number of things are driving this interest in stablecoins today.
Stablecoin use has exploded. Adjusted transaction volume grew 91% in 2025 to $10.9 trillion, approaching Visa’s $14.2 trillion, and real-world payments more than doubled to about $390 billion. As I’ve covered in this column before, stablecoins offer a valuable alternative to traditional payment rails. They are real-time, have greater traceability and transparency, and operate at a lower cost.
Regulation is starting to create clarity around the model. For example, the GENIUS Act enacted licensing requirements and the Fed has proposed reserve and capital rules.
In parallel, real-time domestic payment rails are taking off – think UPI in India, Pix in Brazil and even FedNow domestically in the US – which makes real-time transacting internationally all the more valuable. Lastly, AI agents need native money rails, and many have argued stablecoins may be this use case.
Profile 1: Bridge Acquired By Stripe
Bridge is the first of the large stablecoin acquisitions, scaling from founding to exit in 2.5 years.
Founders Zach Abrams and Sean Yu started the company in 2022. They previously worked at Square and Coinbase, and were backed by Sequoia, Ribbit, Index and Haun Ventures, raising approximately $60m.
In the post-FTX downturn, the company originally offered NFT payments and pivoted to stablecoins over time. At exit, the company reportedly had billions in volume. Stripe acquired the company for just over $1b in an exit announced October 2024. Patrick Collison said at the time stablecoins are “room-temperature superconductors for financial services.” Since then, volume has reportedly continued to scale, and Stripe launched Open Standard, a stablecoin consortium including Visa and 140+ businesses.
Profile 2: BVNK Acquired By Mastercard
BVNK was launched earlier than Bridge, in 2021 by Jesse Hemson-Struthers, Chris Harmse and Donald Jackson. The company had scaled to reach over $20B annualized volume by October 2025 with customers like Worldpay, Deel, Rapyd and others.
Interestingly, originally the deal was not supposed to end with Mastercard. Coinbase had won for $2b, which later died. Mastercard purchased instead for a deal valued up to $1.8B ($1.5B base plus $300M contingent).
Profile 3: Tazapay Being Acquired By Circle
Tazapay was founded in 2020 by Rahul Shinghal, Saroj Mishra and Arul Kumaravel as an escrow platform for cross-border trade. Shinghal previously ran Stripe’s APAC business. In 2026, they evolved into infrastructure. Circle Ventures was already an investor, first in the Series B in 2025 and later leading an extension in 2026. The company is being acquired for $400m in stock, approximately 2x its last valuation, expected to close next year.
The Pattern And What’s Evolving
These are three different transactions, in different geographies with different buyer types. But there are a few commonalities. First, the buyer was able to purchase demonstrated traction, key networks and licenses. Second, different buyer types are interested in this category and bring different value-adds. Third, the cap table was part of the buyer list. This is most clear with Tazapay, purchased by an investor. Coinbase Ventures, a potential acquirer, was itself an investor in both Tazapay and BVNK. Sequoia was an investor in both Bridge and Stripe. And Visa (ironically not the ultimate buyer) was an investor in BVNK.
A few observations that may be evolving in the category: stablecoin issuers are purchasing more of the associated infrastructure, or building it. Clearly Circle is the example here. A Fluent portfolio company (the fund I work at) is Avenia, which in many ways is the Bridge of Brazil and operates the largest Brazilian domestic currency stablecoin. The trend is going the other direction too, with rails becoming the issuer. Stripe and Bridge launched Open Issuance and its consortium.
New Models Emerging From These Rails
The first exits were infrastructure. As these scale, they open up entirely new business models, some of which are already unicorns.
My favorite example is dollar accounts: ARQ, formerly DolarApp (Latin America) raised $70M from Sequoia and Founders Fund earlier this year offering dollarized bank accounts for emerging market customers. Yellow Card is executing a similar playbook in Africa.
Stablecoins are also changing the game in cards. For example, Rain issues stablecoin-powered cards. They raised a $250M Series C at just under $2b earlier this year, working across 200+ companies. In remittances, players like Félix Pago, a Miami-based startup, raised $200m in equity and credit at a reported $1.4B valuation to offer remittances via WhatsApp.
We are still early in the game. However, I expect a proliferation of exits of “local” Bridge/BVNK players globally, and with this a number of players built on stablecoin rails too.
What do you think?